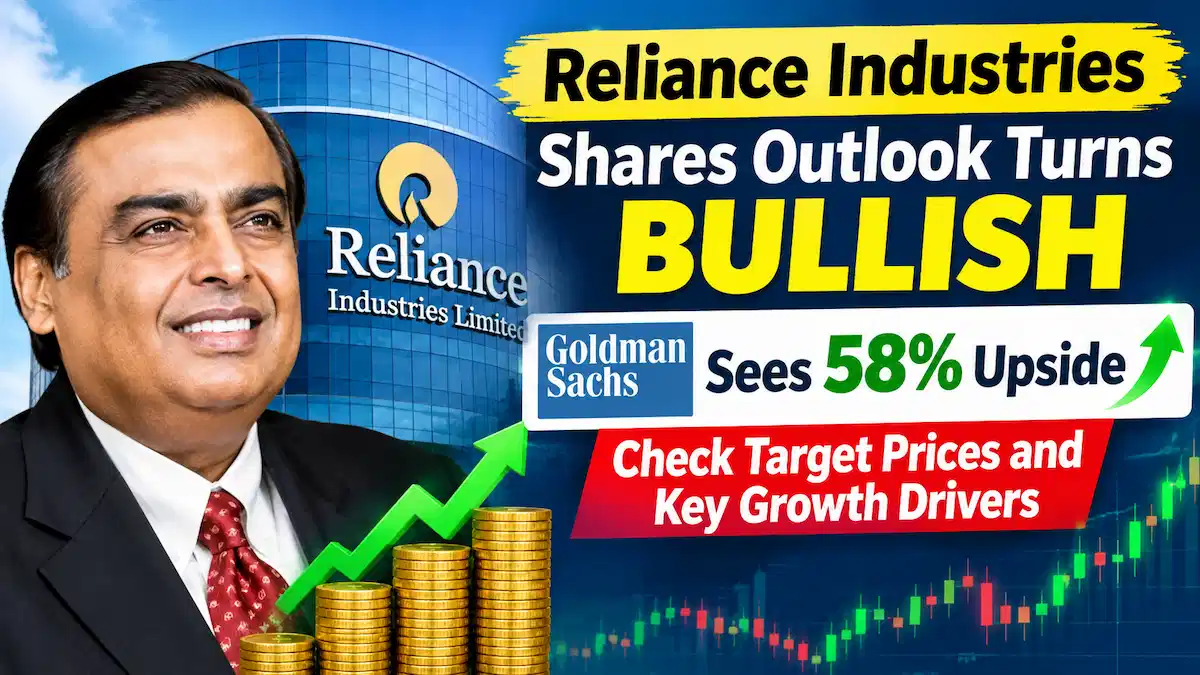
Goldman Sachs and Nomura have both retained their Buy ratings on Reliance Industries Shares Outlook, highlighting the company’s earnings strength and long-term business opportunities. However, weaker retail performance and possible pressure on refining margins remain important concerns for investors.
With brokerage firms projecting significant upside, the big question is whether Reliance Industries shares can deliver further gains in the coming months.
Reliance Industries Share Price and Brokerage Target Prices
Reliance Industries Shares Outlook closed at Rs 1,164.90 on Friday, October 30, slipping 0.21% ahead of the company’s second-quarter results announcement. The company had a market capitalisation of approximately Rs 15.76 lakh crore.
Following the strong quarterly performance, Goldman Sachs and Nomura maintained their Buy recommendations but assigned different target prices.
Here are the key brokerage estimates:
|
Brokerage |
Rating |
Target Price |
|---|---|---|
|
Goldman Sachs |
Buy |
Rs 1,840 |
|
Nomura |
Buy |
Rs 1,560 |
|
Friday Closing Price |
— |
Rs 1,164.90 |
Goldman Sachs’ target indicates approximately 58% upside from the October 30 closing price. Nomura’s target suggests potential upside of around 34% from the same level.
These estimates reflect brokerage expectations, not guaranteed future returns.
Record Q2 Earnings Strengthen Reliance’s Growth Story
Reliance Industries Shares Outlook reported its strongest-ever quarterly financial performance in Q2 FY27, supported by its O2C, digital services and retail businesses.
The company’s consolidated revenue increased 28% year-on-year to a record Rs 3.62 lakh crore. EBITDA climbed 24% to Rs 62,409 crore, while net profit jumped 34% to Rs 29,550 crore.
The O2C business emerged as the biggest contributor to the strong performance.
Its revenue increased 44.2% year-on-year to Rs 2.32 lakh crore, while EBITDA surged 67.9% to Rs 25,203 crore.
The improvement reflects stronger refining and petrochemical conditions, helping Reliance Industries Shares Outlook deliver earnings beyond market expectations.
Goldman Sachs Remains Positive With Rs 1,840 Target
Goldman Sachs maintained its Buy rating and set a target price of Rs 1,840 per share.
The brokerage noted that Reliance’s Q2 EBITDA exceeded its estimates by 9%, primarily because of the stronger-than-expected O2C performance.
However, Goldman Sachs also highlighted a possible challenge for the coming quarters. Higher very large crude carrier (VLCC) freight costs could put pressure on refining margins in Q3.
The brokerage expects some of this pressure to be offset by the company’s ability to process discounted heavy crude.
Reliance’s new energy business also remains an important long-term growth opportunity, with solar manufacturing capacity expansion and battery-related projects progressing.
Nomura Sees Potential Upside With Rs 1,560 Target
Nomura has also maintained its Buy recommendation on Reliance Industries Shares Outlook, setting a target price of Rs 1,560.
According to the brokerage, record earnings were supported by exceptionally strong refining cracks, which helped the O2C business deliver impressive results.
Nomura highlighted that consolidated EBITDA increased 19% sequentially and exceeded its estimates by 9%.
The brokerage also noted steady growth in the telecom business, although retail operations continued to face challenges.
Its valuation assessment places Reliance Industries Shares Outlook at 8.7 times estimated FY28 enterprise value to EBITDA and 16.5 times estimated FY28 price-to-earnings.
Jio Growth Supports Outlook, But Retail Remains a Concern
Reliance’s telecom business continues to provide stability to the company’s overall growth story. Its digital services operations remain an important earnings driver, supported by demand for connectivity and digital platforms.
However, the retail business requires closer attention.
Reliance Retail’s EBITDA declined 11% year-on-year, while revenue growth slowed to 6.4% from 11% in the previous quarter. Its EBITDA margin also contracted by 140 basis points.
The timing of festive demand and investments in JioMart were among the factors affecting performance.
For investors, the coming quarters will be important in determining whether retail growth improves while O2C earnings and telecom operations maintain their momentum.
FAQs
Goldman Sachs has maintained a Buy rating on Reliance Industries with a target price of Rs 1,840 per share, indicating approximately 58% upside from the October 30 closing price of Rs 1,164.90.
Nomura has maintained its Buy recommendation and assigned a target price of Rs 1,560 per share, suggesting approximately 34% upside from the October 30 closing price.
Strong O2C earnings, record Q2 FY27 financial results, steady Jio growth and long-term opportunities in renewable energy are supporting the positive outlook. However, weaker retail performance and potential pressure on refining margins remain key risks. 1. What is Goldman Sachs' target price for Reliance Industries shares?
2. What is Nomura's target price for Reliance Industries?
3. Why are Reliance Industries shares attracting bullish analyst ratings?

Sudhanshu is the author of XYZ News Live and has over 2 years of experience in digital content writing. His focus is on presenting news and important information in a simple, clear, and accessible language for readers.
1 thought on “Reliance Industries Shares Outlook Turns Bullish: Goldman Sachs Sees 58% Upside, Check Target Prices and Key Growth Drivers”